Aquaculture Financing
Financing built for aquaculture - where seasonal inputs and equipment front-load the cost.
See what you qualify for
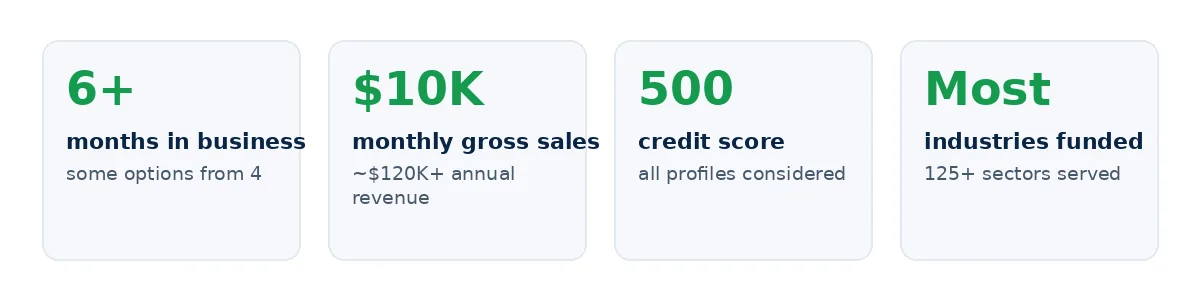
months in business
monthly sales
credit score
- Farming front-loads seed, feed, fertilizer, and equipment costs long before harvest income arrives.
- Equipment financing funds tractors, irrigation, and machinery over their useful life, often using the asset as collateral.
- Working capital bridges the long gap between the cost of a season and the income it produces.
- Lines of credit cover fuel, labor, and inputs across a season, repaid at harvest.
- Most agricultural financing funds in 1-5 business days; equipment terms track the asset's life.
Why aquaculture businesses need financing
Aquaculture businesses run into a familiar cash-flow problem: seasonal inputs and equipment front-load the cost. The fix is not more volume - it is capital timed to that gap.
Because seasonal inputs and equipment front-load the cost, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Seed, feed, and fertilizer bought up front
- Machinery and irrigation
- Bridging the gap to harvest income
- Fuel and labor across a long season
Financing options for aquaculture
The mix below fits the way aquaculture businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
How the money fits aquaculture cash flow
Agriculture has one of the longest cash cycles of any industry: inputs - seed, fertilizer, feed, fuel, and labor - are bought up front, but income arrives only at harvest. Weather and commodity prices add unpredictability to a gap that already runs most of a year.
Financing suited to farming is timed to that cycle. Equipment financing spreads the cost of tractors and irrigation over the years they work, using the machinery as collateral. A line of credit covers the season's running costs, repaid when the crop or livestock income lands.
A row-crop farm spends $180,000 on seed, fertilizer, and fuel in spring, but most of the income arrives after harvest. A line of credit funds the season's inputs, repaid as the crop sells, keeping the operation solvent through the lean months.
When the farm needs a new tractor and an irrigation upgrade, equipment financing spreads the cost across their working lives, with the machinery securing the loan to ease approval.
Cost, speed, and what to have ready
Working capital and lines of credit commonly fund in one to three business days; equipment financing in two to five. Have business bank statements, equipment quotes or input plans, and business information ready. Seasonal repayment structures are commonly available to match your income cycle.
What you need to qualify
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your aquaculture business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →