Compare Financing Options
Two options, side by side - costs, terms, timing, and which one fits your business.
Business Line of Credit vs Term Loan
Both give you capital - but one is a reusable pool you draw from, and the other is a lump sum with fixed payments. Here is how to choose.
Merchant Cash Advance vs Term Loan
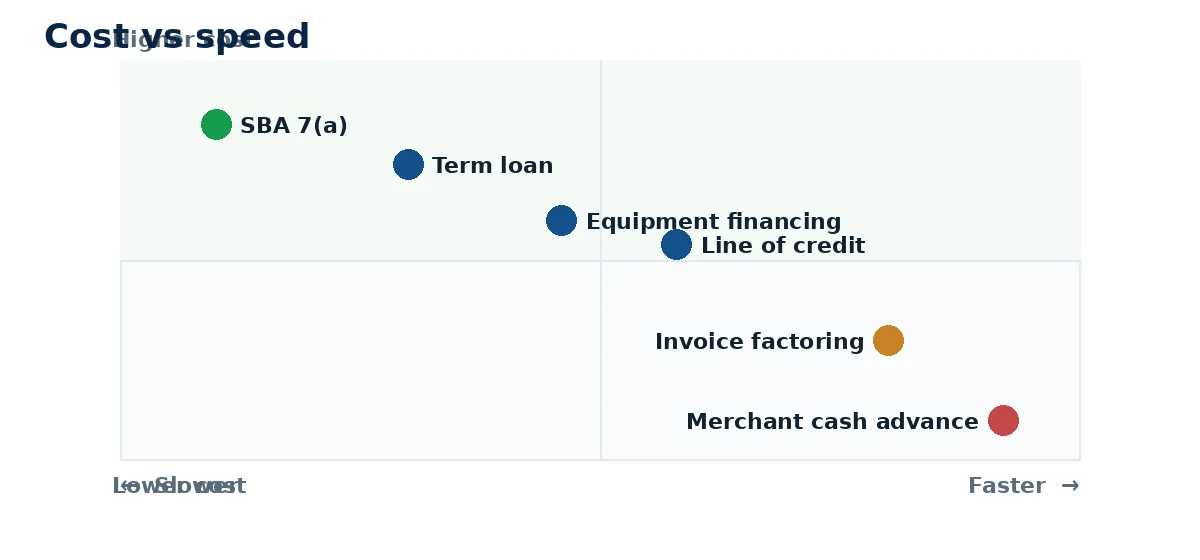
An MCA trades higher cost for speed and repayment that flexes with sales. A term loan costs less but comes with fixed payments. Pick by what your cash flow can handle.
SBA Loan vs Term Loan
SBA loans offer the lowest rates and longest terms in exchange for more paperwork and time. A conventional term loan is faster and simpler.
Invoice Factoring vs Business Line of Credit
Factoring turns your unpaid invoices into cash now. A line of credit gives you a reusable pool to draw from. Which fits depends on where your money is stuck.
Equipment Financing (buy) vs Equipment Lease
Buying builds equity and can be cheaper long-term; leasing preserves cash and keeps you current with technology. Both keep your working capital free.
Working Capital Loan vs Business Line of Credit
Working capital is a fixed lump sum; a line of credit is a reusable pool. One is a decision, the other is a facility.
SBA 7(a) vs SBA 504
7(a) is the flexible, general-purpose SBA program. 504 is built for fixed assets - real estate and heavy equipment - with long, fixed terms.
Purchase Order Financing vs Invoice Factoring
PO financing funds the goods so you can fill an order you could not afford up front. Factoring unlocks capital from invoices you have already issued. One is before the sale, one is after.
Merchant Cash Advance vs Business Line of Credit
An MCA is fast capital repaid from sales. A line of credit is lower-cost, reusable capital. Choose on cost versus speed and repayment style.
Term Loan vs Equipment Financing
A term loan is flexible cash for any purpose; equipment financing is tied to a specific asset, which can mean better terms.
Invoice Factoring vs Purchase Order Financing
Factoring is for money you are owed; PO financing is for orders you cannot yet afford to fill. Same cash-flow idea, opposite end of the cycle.
Commercial Real Estate Loan vs SBA 504
Both finance property. SBA 504 pairs a bank loan with a CDC second loan for lower down payments and long fixed terms; conventional CRE is faster and simpler.
Inventory Financing vs Business Line of Credit
Inventory financing uses your stock as collateral to buy more stock. A line of credit gives you unsecured flexibility. Choose by whether inventory is the bottleneck.
Working Capital Loan vs Merchant Cash Advance
Both put money in your account fast. Working capital gives you fixed payments; an MCA repays from a slice of sales. Choose by cost and cash-flow shape.
Not sure which fits? See what you qualify for
Free, no obligation, and it won't affect your credit.
Get Started →