Term Loan vs Equipment Financing
A term loan is flexible cash for any purpose; equipment financing is tied to a specific asset, which can mean better terms.
See what you qualify for
months in business
monthly sales
credit score
- A term loan is unsecured and flexible; equipment financing is tied to a specific asset that secures the deal.
- Equipment financing often carries better rates and terms because the asset backs it.
- Use equipment financing when you know exactly what you are buying; a term loan when you need general capital.
- Both are quick - days, not weeks - with equipment financing sometimes slightly slower to fund.
Term Loan vs Equipment Financing at a glance
| Term Loan | Equipment Financing | |
|---|---|---|
| Use of funds | Any business purpose | The specific equipment |
| Collateral | Generally unsecured | The equipment itself |
| Terms | ~6 months - 10 years | Matches equipment life |
| Qualification | Broader | Asset-backed, often easier |
| Best for | General capital | Trucks, machinery, technology |
Choose Term Loan if…
- Capital for a mix of purposes
- You are not buying a specific asset
- Flexibility
Choose Equipment Financing if…
- You are buying identifiable equipment
- You want the asset to help secure the deal
- Longer terms tied to asset life
Secured versus flexible
A term loan is, in most cases, unsecured: you borrow a sum and repay it, and the lender's protection is your credit and cash flow rather than a specific asset. That flexibility is its whole value - you can deploy the capital however the business needs it.
Equipment financing is the opposite: it is tied to the asset you are buying, and that asset becomes the lender's collateral. The trade is freedom for security - and sellers of capital reward security with better terms.
So the first question is whether the money is for a specific, identifiable asset. If it is, equipment financing usually aligns better. If it is for a mix of purposes, a term loan keeps your options open.
Why equipment financing often wins on terms
Because the equipment secures the loan, the lender's risk is lower, and that usually shows up in the rate and the length of the term. Terms are commonly matched to the useful life of the asset, so a durable machine can be financed over several years with payments that line up with how long it earns for you.
The collateral effect also improves approval odds. A business with a leaner credit profile can often qualify for equipment financing that a comparable unsecured term loan would not clear, because the lender can recover value from the asset if things go wrong.
For a business buying a truck, a machine, a build-out, or essential technology, that combination of better pricing and easier approval is hard to beat.
Where a term loan wins
A term loan wins when the need is not a single asset. Covering a cash-flow gap, funding marketing, hiring, buying inventory, refinancing other debt, or a mix of these - none of them come with collateral to pledge, and all of them fit a term loan.
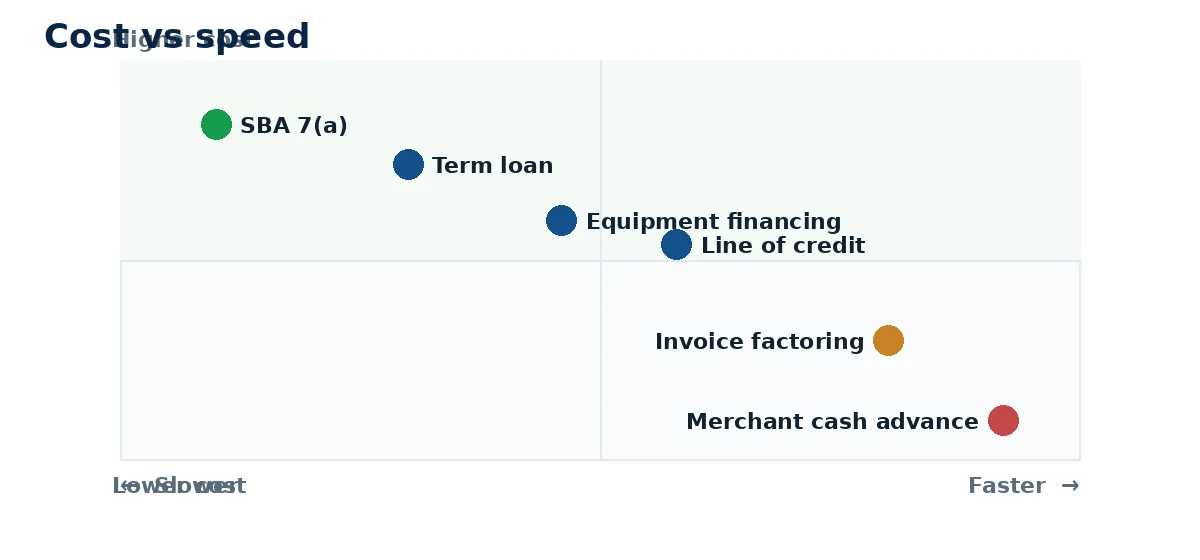
It also wins on speed in some cases and on simplicity always: one loan, no asset schedule, no supplier coordination. If you value having capital you can point at whatever serves the business best, the freedom is worth the potentially higher cost.
How to choose in practice
Ask whether you can name the asset. If the answer is a specific truck, machine, or piece of equipment, price equipment financing first - it will usually be the better deal and the easier approval. If the answer is 'operating the business', a term loan is the right shape.
Pay attention to terms in both cases. Equipment financing should roughly track the asset's useful life - do not finance a five-year asset over one year if the payments would strain cash flow, and do not stretch a deal beyond the asset's working life.
And keep the totals visible: compare the all-in cost of each over the same horizon, not just the monthly payment.
The verdict
If the money is for equipment, equipment financing usually wins on terms and approval odds. If the need is broader, a term loan gives you freedom to deploy the capital.
Comparison shopping is easier with actual offers. Check what you qualify for in minutes - it won’t affect your credit.