Chiropractor Financing
Financing built for chiropractor - where equipment, staffing, and receivables are constant.
See what you qualify for
months in business
monthly sales
credit score
- Healthcare practices carry constant equipment, staffing, and receivables that lag real revenue.
- Equipment financing funds chairs, imaging, and technology that patients expect, matched to the asset's life.
- Working capital and lines of credit cover payroll between insurance reimbursements.
- Slow-paying insurers can strain a busy practice even when patient volume is strong.
- Asset-backed financing often funds in 2-5 business days and can help approval with a lean credit profile.
Why chiropractor businesses need financing
Chiropractor businesses run into a familiar cash-flow problem: equipment, staffing, and receivables are constant. Matching the financing to that rhythm is what keeps operations steady.
Because equipment, staffing, and receivables are constant, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Equipment and technology that patients expect
- Payroll between insurance reimbursements
- Expanding or outfitting a new location
- Covering receivables that arrive slowly
Financing options for chiropractor
The mix below fits the way chiropractor businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
How the money fits chiropractor cash flow
A practice buys equipment and pays staff on a schedule, but is reimbursed by insurers on a slower one - often 30 to 90 days after treatment. That lag, plus the constant pressure to invest in technology patients now expect, makes steady capital a practical necessity rather than a luxury.
The right mix pairs equipment financing for clinical assets with a working capital facility for the reimbursement gap. Equipment-backed terms track the useful life of the chair or scanner; a line of credit covers payroll and overhead while claims are processed.
A dental practice adds two operatories and a cone-beam scanner at $180,000, expecting $30,000 a month in new production. Equipment financing spreads the cost over five years, and the new revenue services the payment with room to spare.
Meanwhile, a line of credit covers two months of payroll while a new insurance contract's claims work through the system - repaid automatically as reimbursements land.
Cost, speed, and what to have ready
Equipment financing commonly funds in two to five business days; working capital and lines in one to three. Have business bank statements, equipment quotes or asset details, and business information ready. Because clinical assets secure much of the financing, approval can be more attainable than for unsecured lending.
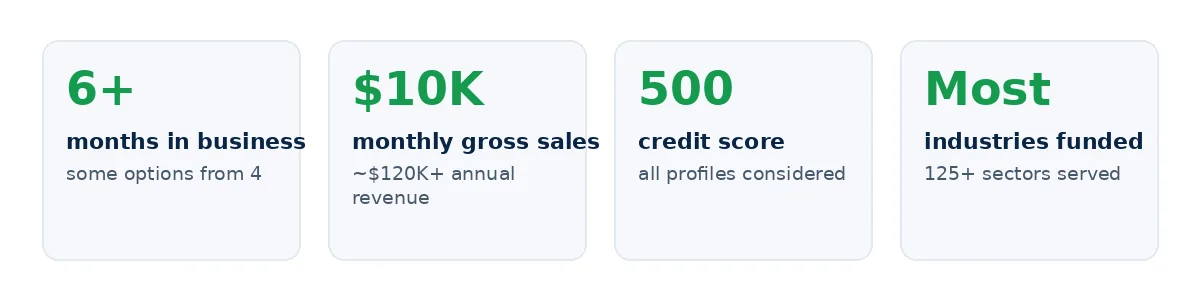
What you need to qualify
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your chiropractor business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →