Tattoo Studio Financing
Financing built for tattoo studio - where equipment, build-outs, and supplies come first.
See what you qualify for
months in business
monthly sales
credit score
- Personal-service businesses spend on equipment, build-outs, and supplies before the clients arrive.
- Equipment financing funds the chair, station, or vehicle without a large cash outlay.
- Working capital and lines of credit cover the slow ramp after opening and seasonal swings.
- Lines of credit are reusable, covering recurring needs as the client base grows.
- Most personal-service financing funds in 1-5 business days with light documentation.
Why tattoo studio businesses need financing
Tattoo Studio businesses run into a familiar cash-flow problem: equipment, build-outs, and supplies come first. Matching the financing to that rhythm is what keeps operations steady.
Because equipment, build-outs, and supplies come first, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Equipment and build-outs for the space
- Inventory and supplies
- Covering the slow ramp after opening
- Taking on more clients or customers
Financing options for tattoo studio
The mix below fits the way tattoo studio businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
How the money fits tattoo studio cash flow
For salons, spas, fitness studios, and similar businesses, the money goes out before the customers come in: equipment, a build-out, supplies, and staff, all funded on the promise of future bookings. The first months are a ramp, and seasonal swings come later.
Equipment financing handles the stations, chairs, and vehicles so the up-front cost is spread. A line of credit absorbs the slow ramp after opening and the seasonal dips, and working capital funds a defined investment in growth.
A new salon opening six stations spends $45,000 on chairs, stations, and build-out before its first client walks in. Equipment financing spreads that over the assets' life, keeping cash free for the first months of operating costs.
A line of credit covers the slower summer weeks in year two, repaid through the busier autumn as bookings fill.
Cost, speed, and what to have ready
Equipment financing funds in two to five business days; lines of credit in one to three. Have business bank statements, equipment quotes, and business information ready. Asset-backed terms make this category accessible even for newer personal-service businesses.
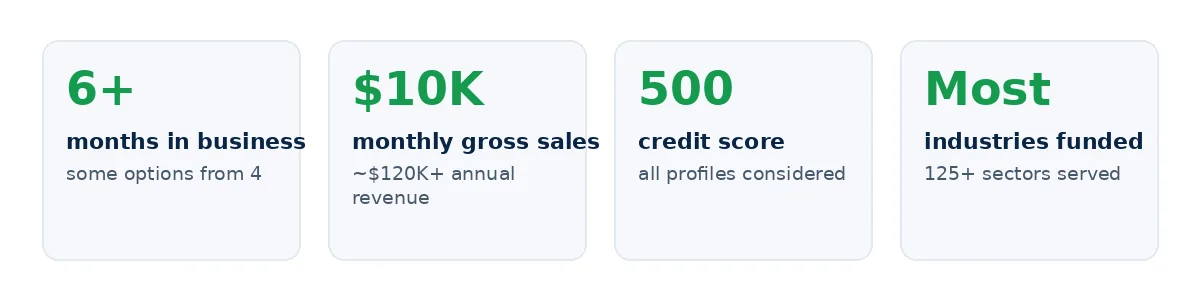
What you need to qualify
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your tattoo studio business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →