Adult Financing
Financing built for adult - where receivables and payroll rarely line up.
See what you qualify for
months in business
monthly sales
credit score
- For professional services, receivables and payroll rarely line up - clients pay in 30-90 days.
- A line of credit is the workhorse: reusable, flexible for payroll, hiring, and overhead.
- Invoice factoring accelerates slow-paying client invoices and is underwritten on your clients' credit.
- Working capital handles a defined gap with a clean payoff.
- Most professional-services financing funds in 1-3 business days with light documentation.
Why adult businesses need financing
Adult businesses run into a familiar cash-flow problem: receivables and payroll rarely line up. The right facility closes that gap without slowing the work down.
Because receivables and payroll rarely line up, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Payroll while client invoices age
- Software, hiring, and office costs
- Investing in business development
- Covering seasonal swings in billings
Financing options for adult
The mix below fits the way adult businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Invoice Factoring
Turn unpaid invoices into immediate cash. Funding against invoices aged up to 90 days - $100K+.
How the money fits adult cash flow
A professional practice bills after delivering, and clients pay on their own schedule - often 30, 60, or 90 days later. Payroll, however, arrives every two weeks like clockwork. That mismatch means growth is constrained by how long cash takes to come back, not by demand for the work.
A line of credit bridges the gap and is reusable, so it handles the recurring rhythm of billings rather than a single event. Factoring accelerates specific slow invoices against the strength of your clients' credit, and working capital covers a defined need with a clear payoff.
An agency doing $150,000 a month in billings on 60-day terms must fund roughly two months of payroll - say $180,000 - before that revenue lands. A line of credit covers the gap and is repaid as invoices are collected.
When a single large client stretches payments to 90 days, factoring that specific invoice converts it to cash immediately, backed by the client's creditworthiness rather than the agency's balance sheet.
Cost, speed, and what to have ready
Lines of credit and working capital commonly fund in one to three business days; factoring in one to two. Have three to six months of business bank statements, a client or invoice summary, and business information ready. Factoring leans on your customers' credit, which can help newer or lower-credit firms.
What you need to qualify
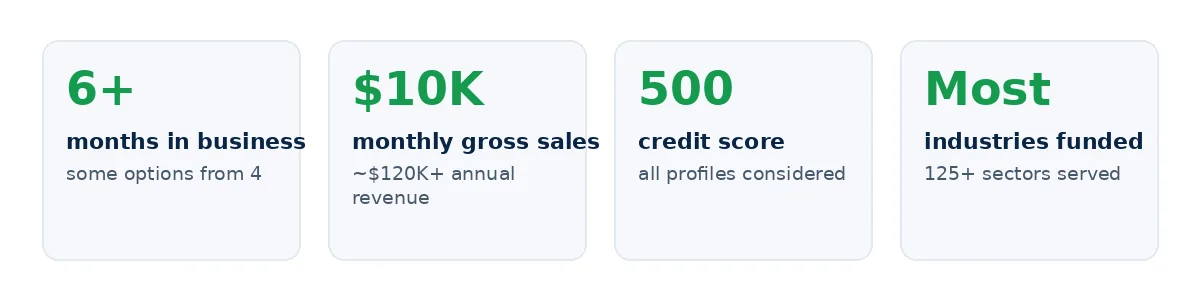
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your adult business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →