Boat Dealer Financing
Financing built for boat dealer - where invoices and fuel costs move faster than the cash arrives.
See what you qualify for
months in business
monthly sales
credit score
- Trucking and transport cash flow is squeezed by fuel, payroll, and repairs that are due now while broker payments arrive in 30-60 days.
- Invoice factoring advances cash against each delivered load within a day or two, and scales with your volume.
- A working capital loan or line of credit covers the gaps factoring cannot - repairs, insurance, payroll timing.
- Equipment financing spreads the cost of adding trucks or trailers over the years they earn.
- Most transport financing funds in 1-5 business days, with equipment acting as collateral to help approval.
Why boat dealer businesses need financing
Boat Dealer businesses run into a familiar cash-flow problem: invoices and fuel costs move faster than the cash arrives. Timing the capital to the cycle is the difference between stalling and scaling.
Because invoices and fuel costs move faster than the cash arrives, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Fuel and driver payroll between loads
- Repairs when a truck is down and revenue stops
- Adding trucks or trailers to take on more freight
- Covering the 30-60 day wait on broker payments
Financing options for boat dealer
The mix below fits the way boat dealer businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Invoice Factoring
Turn unpaid invoices into immediate cash. Funding against invoices aged up to 90 days - $100K+.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
How the money fits boat dealer cash flow
A carrier pays for fuel this week and driver payroll on Friday, but the load it just delivered may not be paid for 45 days. That permanent lag is the defining fact of transport cash flow - and the reason a profitable operation can still feel starved of cash.
The right financing is timed to that gap rather than to an emergency. Factoring turns a delivered load into cash immediately; a working capital facility absorbs the surprise repair that is not tied to any invoice; equipment financing adds capacity without draining the cash you need for fuel and payroll.
Take a two-truck operation running $60,000 of loads a month on 45-day broker terms. Fuel and driver pay alone might be $40,000 a month due immediately - a month and a half of cost the carrier must fund before a single dollar of that revenue arrives.
Factoring the loads closes most of that gap within days. A line of credit covers the transmission repair that lands on a Wednesday. When the owner adds a third truck, equipment financing spreads the cost over the asset's life instead of gutting working capital.
Cost, speed, and what to have ready
Factoring and equipment financing can fund in one to five business days with basic documentation - bank statements, load or asset details, and business information. Terms track the asset's life for equipment and your receivable volume for factoring, so pricing improves as your fleet and invoices grow.
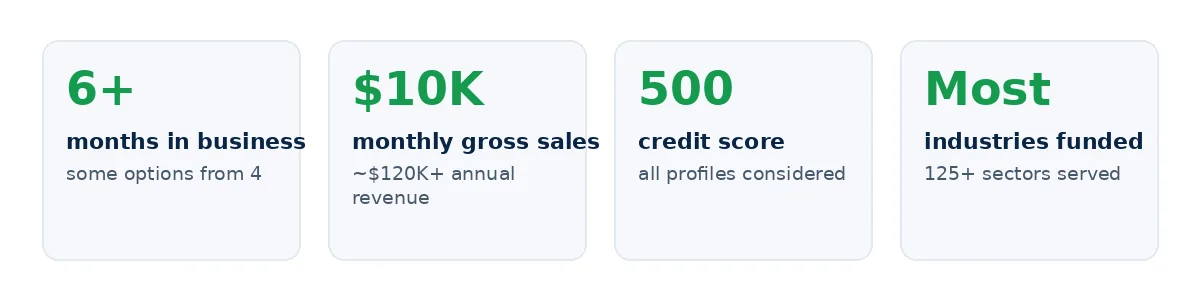
What you need to qualify
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your boat dealer business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →