Brewery Financing
Financing built for brewery - where payroll, inventory, and slow nights do not wait.
See what you qualify for
months in business
monthly sales
credit score
- Restaurants and food businesses face payroll, inventory, and slow nights that will not wait for a good month.
- Working capital and a line of credit smooth the seasonal and weekly swings of food service.
- Equipment financing covers ovens, refrigeration, and build-outs without a large cash outlay.
- An MCA can fund fast for a genuine emergency like a failed cooler, but costs more than cheaper alternatives.
- Many food businesses fund in 1-3 business days, with repayment structured around daily sales.
Why brewery businesses need financing
Brewery businesses run into a familiar cash-flow problem: payroll, inventory, and slow nights do not wait. Matching the financing to that rhythm is what keeps operations steady.
Because payroll, inventory, and slow nights do not wait, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Payroll through slow nights and off-seasons
- Inventory and supplies bought in bulk
- A build-out or equipment upgrade
- Tiding over the gap between a lease and a busy season
Financing options for brewery
The mix below fits the way brewery businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
Merchant Cash Advance
Revenue-based funding repaid as you sell - fast capital for businesses that take card or daily sales.
How the money fits brewery cash flow
A restaurant's costs are fixed and daily - payroll, rent, food, utilities - while revenue swings with seasons, weather, and slow weeknights. That mismatch means a single bad month can strain an otherwise healthy business, and a failed piece of equipment can threaten a weekend's takings.
Financing suited to food service matches that rhythm. A line of credit covers the slow stretches and is repaid when trade picks up; working capital handles a defined project like a build-out; equipment financing replaces the oven or walk-in without draining cash.
Imagine a restaurant doing $85,000 a month that loses its main cooler on a Friday. Replacing it costs $18,000 and cannot wait - the weekend alone might be $12,000 of revenue. A fast facility funds the replacement in a day or two, repaid over the following months.
For the slower annual cycle, a line of credit covers the off-season payroll and is paid down through the busy months. Equipment financing handles planned upgrades - a new range, a POS system - spreading the cost over their working life.
Cost, speed, and what to have ready
Many food-service options fund in one to three business days, with repayment often structured as a percentage of daily or weekly sales to match your takings. Have three to six months of business bank statements and basic business information ready. Loose requirements make this one of the more accessible financing categories for newer restaurants.
What you need to qualify
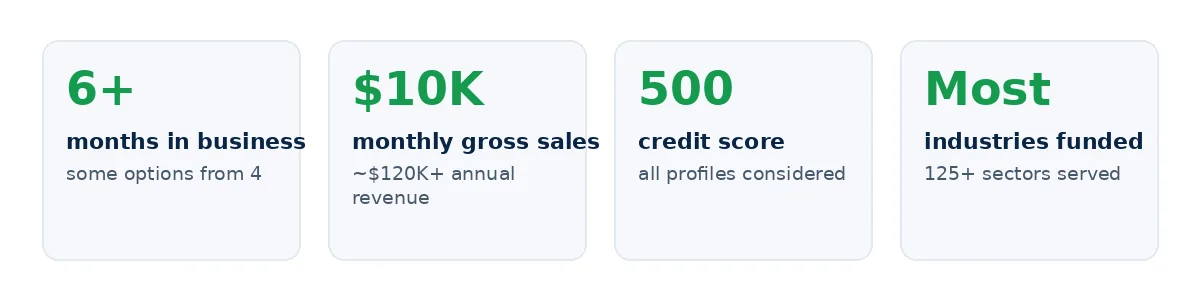
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your brewery business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →