Small Business Financing in Creve Coeur, MO
Working capital, lines of credit, SBA, equipment and factoring for Creve Coeur businesses - from $10,000 to $5,000,000.
- Funding in as little as 1-3 business days
- All credit profiles considered
- Checking won’t affect your credit
- No obligation
See Creve Coeur options
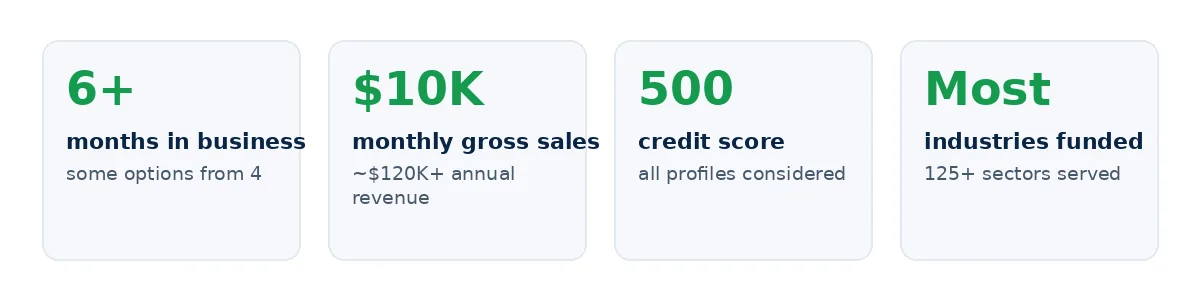
months in business
monthly sales
credit score
- Creve Coeur businesses in agriculture, manufacturing, and logistics often need capital that keeps pace with high rent and overhead leave little room for a slow month.
- Working capital, lines of credit, and factoring are the most common fits for Creve Coeur operators.
- Most Creve Coeur financing funds in 1-3 business days, and checking your options is a soft inquiry.
- Equipment financing can use the asset as collateral, which helps approval with a lean credit profile.
Financing options for Creve Coeur businesses
As a center for agriculture and manufacturing, Creve Coeur runs on businesses that have to move fast - and high rent and overhead leave little room for a slow month. Working capital, lines of credit, equipment financing, and factoring close that gap so you can take the next job, hire, or cover a slow stretch without stalling.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
SBA Loans
SBA-backed financing with lower rates and longer terms for growth, equipment, or working capital. $10,000 to $5,000,000.
Invoice Factoring
Turn unpaid invoices into immediate cash. Funding against invoices aged up to 90 days - $100K+.
Commercial Real Estate Loans
Finance the purchase, refinance, or renovation of commercial property from $250,000 to $10,000,000.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Creve Coeur, MO at a glance
Residents in Creve Coeur
the #2049 largest city by population in the US across the metro area
Financing range
across 11 products
Typical funding time
for working capital and lines of credit
Why Creve Coeur businesses need flexible capital
Creve Coeur and the wider MO market are built on sectors like agriculture, manufacturing, and logistics. In businesses like these, high rent and overhead leave little room for a slow month - which is exactly the kind of timing gap financing exists to close.
That means the real constraint on growth is rarely demand. It is how long money spent on payroll, supplies, and equipment takes to come back as revenue. A facility timed to that gap keeps a Creve Coeur business moving while it scales.
How Creve Coeur businesses use financing
Creve Coeur operators commonly reach for Working Capital, Business Line of Credit and SBA Loans - each mapped to a different part of the cash-flow cycle.
Because these needs tend to recur, a line of credit is often the most efficient tool: reusable, and repaid as revenue arrives. For a one-time investment, working capital or equipment financing gives a defined payoff, and factoring accelerates slow-paying customer invoices when receivables are the bottleneck.
Popular cities in Missouri
Kansas City, MO
Financing options for Kansas City businesses.
St. Louis, MO
Financing options for St. Louis businesses.
Springfield, MO
Financing options for Springfield businesses.
Columbia, MO
Financing options for Columbia businesses.
Independence, MO
Financing options for Independence businesses.
Lee's Summit, MO
Financing options for Lee's Summit businesses.
O'Fallon, MO
Financing options for O'Fallon businesses.
St. Charles, MO
Financing options for St. Charles businesses.
St. Joseph, MO
Financing options for St. Joseph businesses.
St. Peters, MO
Financing options for St. Peters businesses.
Blue Springs, MO
Financing options for Blue Springs businesses.
Joplin, MO
Financing options for Joplin businesses.
All Missouri cities
See all 80 cities we serve in Missouri.
Nearby cities
Town and Country, MO
Financing for Town and Country businesses - 11,625 residents served.
Maryland Heights, MO
Financing for Maryland Heights businesses - 27,671 residents served.
Overland, MO
Financing for Overland businesses - 15,547 residents served.
St. Ann, MO
Financing for St. Ann businesses - 12,704 residents served.
Kirkwood, MO
Financing for Kirkwood businesses - 29,348 residents served.
University City, MO
Financing for University City businesses - 34,349 residents served.
Clayton, MO
Financing for Clayton businesses - 17,512 residents served.
Manchester, MO
Financing for Manchester businesses - 18,122 residents served.
Frequently asked questions
See how much your Creve Coeur business qualifies for
Free, no obligation, and it won’t affect your credit.
Get Started →