Small Business Loans in South Carolina
From Charleston to Greenville - business financing for South Carolina from $10,000 to $5,000,000.
See South Carolina options
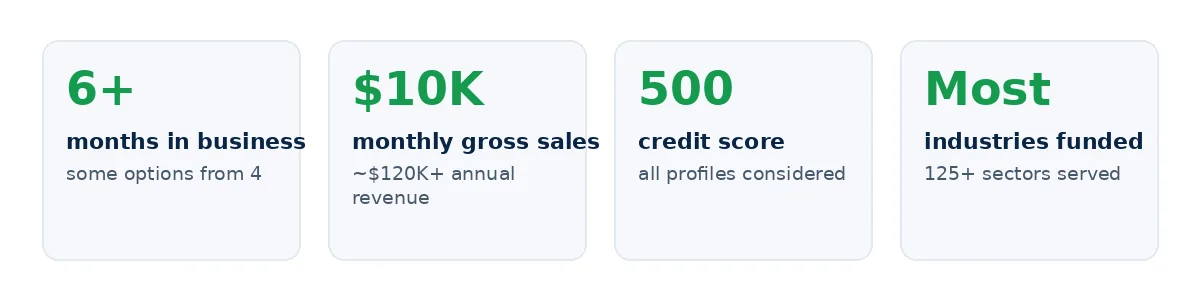
months in business
monthly sales
credit score
- South Carolina's automotive and aerospace supply chains drive equipment and working-capital demand.
- Charleston's port and logistics activity makes factoring a natural fit.
- Coastal tourism businesses use seasonally structured lines of credit.
Financing for South Carolina businesses
Businesses across South Carolina use working capital, lines of credit, equipment financing, and factoring to manage cash flow and grow. One simple application gets you terms that fit your business.
Working Capital
Fast, flexible capital to cover cash-flow gaps, seize opportunities, or invest in growth - from $10,000 to $5,000,000.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
SBA Loans
SBA-backed financing with lower rates and longer terms for growth, equipment, or working capital. $10,000 to $5,000,000.
Invoice Factoring
Turn unpaid invoices into immediate cash. Funding against invoices aged up to 90 days - $100K+.
Commercial Real Estate Loans
Finance the purchase, refinance, or renovation of commercial property from $250,000 to $10,000,000.
Equipment Financing
Fund the trucks, machinery, and technology your business needs - without draining cash flow. $10,000 to $5,000,000.
Cities we serve in South Carolina
The South Carolina business landscape
South Carolina has become an automotive and aerospace manufacturing hub, with a booming coastal tourism sector, agriculture, logistics, and healthcare rounding out the economy. Port activity in Charleston supports growing export industries.
From Charleston's port and tourism economy to the Upstate's manufacturing corridor, businesses need capital that handles production schedules and sharp seasons alike.
Financing in South Carolina today
South Carolina businesses can access working capital, lines of credit, equipment financing, and factoring from $10,000 to $5,000,000. Working-capital options typically fund in one to three business days.
How South Carolina businesses use financing
Businesses across South Carolina - from automotive manufacturing to healthcare - use working capital, lines of credit, equipment financing, and factoring to manage the gap between spending and getting paid.
A line of credit suits recurring needs that flex week to week; working capital fits a defined, one-time investment; equipment financing spreads the cost of trucks, machinery, and technology over the years they earn; and invoice factoring accelerates slow-paying customer invoices when receivables are the bottleneck.
Frequently asked questions
See how much your South Carolina business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →