Equipment Service / Repair Financing
Financing built for equipment service / repair - where seasonal inventory sits on the shelf before it sells.
See what you qualify for
months in business
monthly sales
credit score
- Retail lives on seasonal inventory that must be bought months before it sells.
- Inventory financing uses your stock as collateral to fund more stock, scaling with your shelves.
- A line of credit covers the operating swings - rent, payroll, marketing - beyond inventory.
- An MCA can fund fast but costs more; use it only for genuine urgency.
- Most retail financing funds in 1-5 business days, often with repayment tied to sales.
Why equipment service / repair businesses need financing
Equipment Service / Repair businesses run into a familiar cash-flow problem: seasonal inventory sits on the shelf before it sells. Matching the financing to that rhythm is what keeps operations steady.
Because seasonal inventory sits on the shelf before it sells, the constraint is rarely demand - it is the timing gap between money going out and money coming in. Working capital, a line of credit, or equipment financing absorbs that gap so operations keep moving while you grow.
- Seasonal inventory bought ahead of demand
- A store refresh or new location
- Marketing pushes around key sales periods
- Cash reserves for slow months
Financing options for equipment service / repair
The mix below fits the way equipment service / repair businesses actually operate. Compare as many as you like - checking won’t affect your credit.
Inventory Financing
Stock up ahead of demand without tying up your cash - inventory as collateral.
Merchant Cash Advance
Revenue-based funding repaid as you sell - fast capital for businesses that take card or daily sales.
Business Line of Credit
Revolving capital you draw from when you need it - pay only on what you use. From $10,000 to $5,000,000.
How the money fits equipment service / repair cash flow
A retailer's central problem is timing: you must buy inventory months before customers buy it, and a season's entire bet can sit on the shelf before a dollar of it comes back. The bigger the season you want to chase, the more cash you need up front.
Inventory financing attacks that directly, lending against the stock you already manage so you can stock deeper. A line of credit handles everything else - the rent, the payroll, the marketing push - so a slow month does not become a crisis.
A gift shop wants to stock $120,000 of holiday inventory in September for a December that could bring $260,000 in sales. Inventory financing funds most of the buy against the stock itself, repaid as the season sells through.
A line of credit covers October rent and a holiday marketing push, ensuring the cash that would have gone into overhead instead goes into the inventory that drives the season.
Cost, speed, and what to have ready
Inventory financing and lines of credit commonly fund in one to five business days, with repayment often tied to sales. Have business bank statements, inventory or sales details, and business information ready. Sellable goods with predictable demand are the easiest to finance.
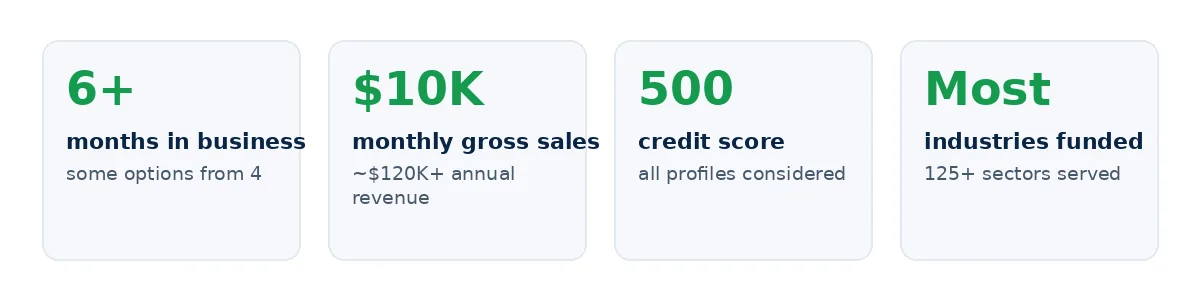
What you need to qualify
Months in business
Some options from 4 months
Monthly gross sales
~$120K+ annual revenue
Credit score
All credit profiles considered
Frequently asked questions
See what your equipment service / repair business qualifies for
Free, no obligation, and it won't affect your credit.
Get Started →